US datacenter buildout meets a packaging ceiling
SynMax estimates US datacenter gross capacity will rise from about 11 GW in 2025 to 16-18 GW in 2026, with 2027 capped in the low 20s.
The wire page reports that satellite imagery shows US datacenter construction accelerating, and the packet has no figure. SynMax, cited in the Jefferies report, tracks land clearing, first structures, and construction progress from weekly imagery. It estimates gross capacity rising from roughly 11 GW in 2025 to 16-18 GW in 2026, above its earlier 14-16 GW forecast.
Die Brief reads the constraint as packaging, not fabs. The document does not prove that die output is scarce; it measures the gap between announced land and the packaged accelerators that can be installed. For a buyer, the binding variable is the date a packaged accelerator reaches the rack, not the wafer lot that produced it. For a fab, the choke point sits downstream, where high-density interconnect and memory attach determine whether a die becomes deployable capacity.
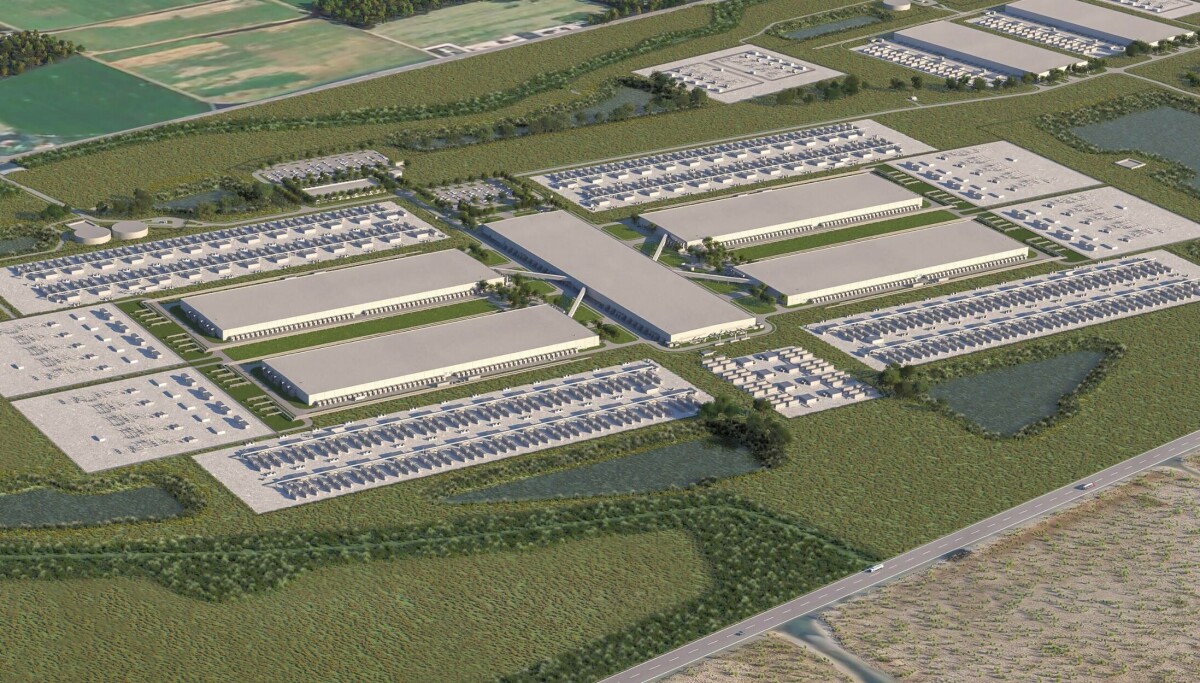
The same page says land clearing has plateaued, leaving visible activity short of the pace needed for more than 80 GW implied by announced pipelines and chip demand models for 2028. An earlier Jefferies report found only half of the US capacity scheduled for 2026 under construction, with work not begun on as much as 80 percent of the 2028 pipeline. Development is concentrated in Texas and Virginia, so national totals remain exposed to local grid delays.
The page leaves out the yield of packaging lines, the mix of accelerator models, and the power draw of each installed server. It also does not measure how much of the 2028 pipeline is actually under contract, funded, or permitted. The 13 GW accelerator-equivalent and 17.5 GW total datacenter figures are estimates, not a measured inventory of available packages. The two 2027 projects add another 6 GW only if they come online as expected.
Die Brief reads the constraint as packaging, not fabs. The binding variable for buyers is the date a packaged accelerator reaches the rack, not the wafer lot that produced it.
The document does not measure packaging yield, accelerator mix, or the actual power draw of installed servers.
The limiting step is advanced packaging: die output becomes deployable only after high-density interconnect and memory attach are complete. Fab capacity alone does not determine datacenter power, because packaging throughput and yield set the installable accelerator count.
11 GW gross capacity in 2025 · 16-18 GW in 2026 · low 20s GW practical ceiling for 2027 · 13 GW accelerator-equivalent packaging capacity · 17.5 GW total datacenter power · 6 GW from two 2027 packaging projects
After The Register. We did not report this. The pictures, if any, are theirs.